Victory’s North Stanmore PFS outlines a proposed 20-year heavy rare earth operation with A$1.21 billion post-tax NPV8 and A$155 million initial capital.
Mining Lease M20/564 has been granted, while pilot-plant concentrate is undergoing qualification by potential partners in Australia, Japan and the United States.
The project still requires further feasibility work, approvals, commercial agreements and funding before any construction or production decision.
Victory Metals’ 30 October 2026 quarterly activities report presents North Stanmore as a rare earth project moving from exploration and study work toward the more demanding stages of tenure, product qualification and financing. The company reported a completed Pre-Feasibility Study, a maiden Probable Ore Reserve, an updated Mineral Resource Estimate and the grant of Mining Lease M20/564 in Western Australia’s Cue region. It also confirmed that heavy rare earth concentrate had been dispatched to potential partners in Australia, Japan and the United States.
A large study case, but not yet a mine
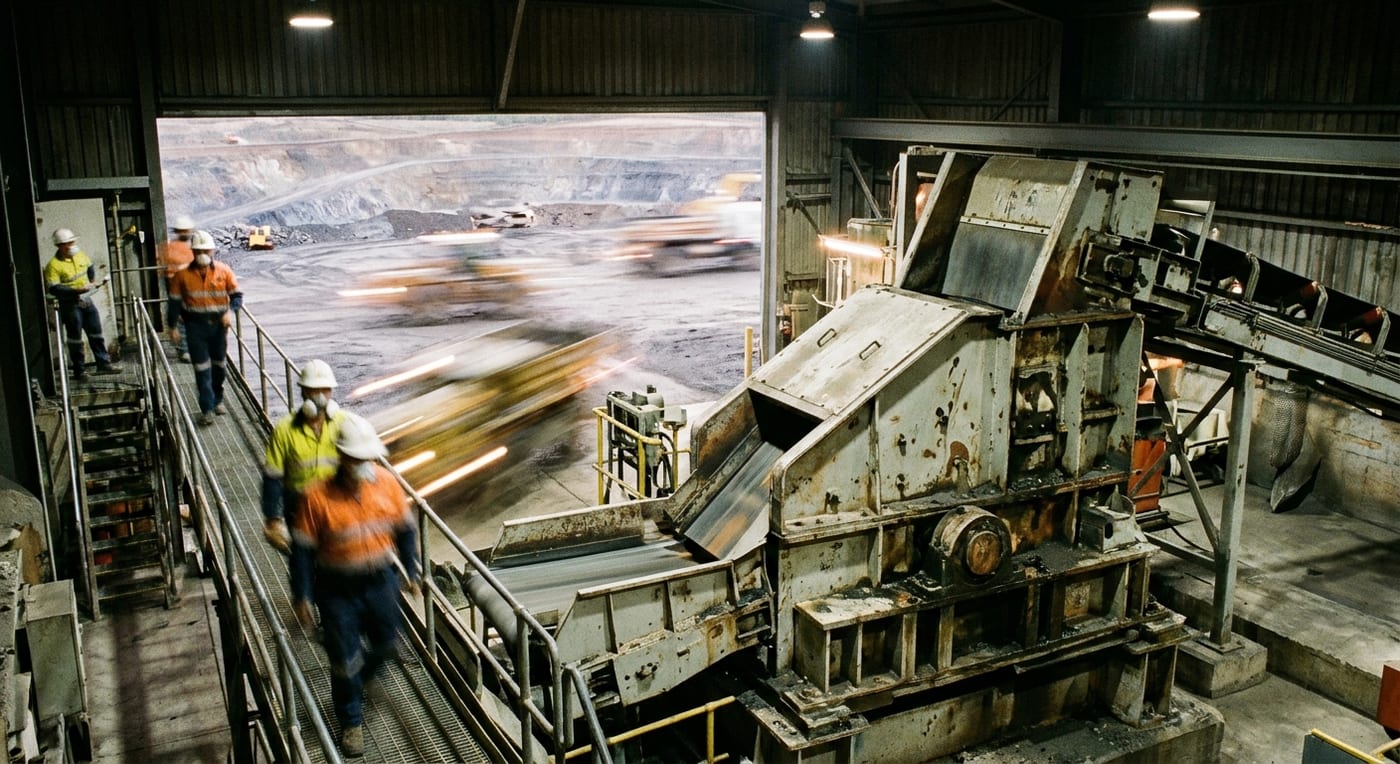
The North Stanmore PFS outlines a proposed 20-year development based on shallow, predominantly free-dig open-pit mining and flotation beneficiation. The concept assumes plant throughput of 2.4 million tonnes per annum, with approximately 29,000 wet tonnes of heavy rare earth-enriched concentrate produced each year for sale to third-party refiners.
The study reports life-of-mine free-on-board revenue of A$6.5 billion, initial capital of A$155 million including a 30% contingency, and post-tax NPV8 of A$1.21 billion with a post-tax IRR of 240%. Its pre-tax NPV8 is A$1.762 billion, with a pre-tax IRR of 338% and an estimated payback period of about 1.5 years from first production.
Those figures are study outcomes rather than a construction decision or operating result. Victory said the production target is based entirely on the Probable Ore Reserve and excludes Inferred Mineral Resources and Exploration Targets. The company also stated that the PFS uses long-term net payability prices discounted to current spot prices, with 65% payability applied to rare earth oxides and 50% to hafnium oxide.
The maiden Probable Ore Reserve totals 47.0 million tonnes at 692 parts per million TREO and 248 parts per million HREO, containing 32.6 kilotonnes of TREO and 11.6 kilotonnes of HREO. The updated Mineral Resource Estimate totals 278.8 million tonnes at 483 parts per million TREO, including a maiden Measured category of 70.7 million tonnes.
A higher-grade domain of 53.3 million tonnes at 1,024 parts per million TREO remains an important part of the resource profile. Victory said the updated estimate incorporated 83 drill holes covering 4,378 metres, including 20 twin holes intended to confirm existing results. The company also reclassified material previously logged as saprock as saprolite, allowing additional material to be incorporated into the PFS mine plan.
Tenure and customer qualification add development momentum
Mining Lease M20/564 was granted on 11 September 2026 and covers almost 2,006 hectares. The lease secures mining tenure over the relevant North Stanmore area, although it does not remove the need for further technical work, approvals, funding and commercial agreements.
CEO and Executive Director Brendan Clark said, “The grant of our 2,006-hectare Mining Lease is a major milestone for Victory and an important step towards bringing North Stanmore into production.” The grant followed a Native Title Mining Agreement executed with the Wajarri Yamaji Aboriginal Corporation in June 2026, according to the company.
The company’s Perth flotation pilot plant continued operating under steady-state conditions during the quarter, producing a heavy rare earth-enriched concentrate consistent with the 7.1% TREO result previously reported by Victory. Concentrate dispatches began on 9 July 2026, with potential offtake partners in Australia, Japan and the United States conducting independent examination, analysis and qualification.
Brendan Clark said, “Dispatching our heavy rare earth concentrate to these partners in Australia, Japan and the United States for their own independent examination is a significant commercial step.” The report describes discussions with strategic partners across Japan, Europe and the United States, but it does not announce a binding offtake agreement.
Mineralogy supports the proposed processing route, with caveats
TIMA mineralogy work completed by ALS Metallurgy found that most of the targeted rare earth value in the pilot plant concentrate was associated with secondary phosphate groups rather than primary monazite and xenotime. The reported deportment results assigned 86% of dysprosium, 82% of terbium, 96% of yttrium, 88% of praseodymium and 91% of neodymium to secondary phosphate groups.
Victory said this mineralogy supports a wet screening and flotation-led beneficiation route before selective hydrometallurgical treatment. The company also stated that calcium is predominantly hosted in feldspar rather than reactive carbonates, which it considers favourable for acid consumption.
The technical qualification remains incomplete. ALS recorded high uncertainty for praseodymium and neodymium deportment and very high uncertainty for terbium and dysprosium, recommending LA-ICP-MS analysis to refine phase compositions. Victory’s report also cautions that the TIMA study does not establish leach recovery, reagent consumption or final process conditions.
Funding is the next major test
Victory recorded exploration expenditure of A$1.579 million during the quarter, largely related to North Stanmore exploration, metallurgical work, pilot plant operations and PFS completion. Administration and corporate expenditure was A$570,000, including A$188,000 in payments to related parties.
Cash and cash equivalents stood at approximately A$9.18 million at 30 September 2026, compared with A$11.184 million at the beginning of the quarter. The Appendix 5B reported relevant quarterly outgoings of A$2.101 million and estimated 4.37 quarters of funding available on the company’s stated calculation.
The company is reviewing several funding options for the next phase, including a non-binding US EXIM Letter of Interest for up to US$190 million, project debt, strategic equity, offtake-linked funding and government support. A non-binding letter is not a financing commitment, and the report makes clear that funding, approvals, infrastructure, operating costs, metallurgical performance and market conditions remain material risks.
A strategic project in a supportive policy environment
North Stanmore’s focus on dysprosium, terbium and other heavy rare earths aligns with Australia’s broader effort to build more diversified critical minerals supply chains. The Australian Government’s updated 2026 Critical Minerals Strategy identifies secure supply, international partnerships, First Nations engagement and domestic processing as central priorities, while its Critical Minerals Strategic Reserve includes heavy rare earth elements such as dysprosium and terbium.
The project’s resource and reserve disclosures are presented under the 2012 JORC Code, which defines an Ore Reserve as the economically mineable part of a Measured and/or Indicated Mineral Resource after the application of relevant modifying factors. That framework is important because North Stanmore’s headline economics remain dependent on the assumptions and technical work supporting the PFS.
Victory’s next steps are focused on a Definitive Feasibility Study, geotechnical and hydrogeological investigations, engineering definition, further metallurgical testing, product qualification, approvals, offtake discussions and a funding strategy. The quarter therefore marked meaningful progress, but the company remains on the path toward development rather than in production. For North Stanmore, the central question is whether its promising study economics and distinctive mineralogy can be converted into a financeable, permitted and commercially supported operation.