Empress Royalty: A Smarter Way to Play Gold and Silver
This article is disseminated on behalf of Empress Royalty Corp.
- Royalty and streaming model: capital for a share of mine output, without the operating costs - Four producing assets have generated US$47 million in cumulative revenue - Record US$17.2 million revenue in 2025; H1 2026 revenue more than doubled - US$62 million Tongon gold stream closed 19 October 2026, with no equity raised - Trades around 1.0x NAV versus a peer average of roughly 1.45x
Gold is at all time highs. Central banks are buying at record levels. Inflation concerns are not going away. And yet most gold mining stocks have not kept pace with the metal itself.
There is a reason for that. Mining is expensive. Operating costs rise with inflation. Permits take years. Capital expenditures eat into margins. Investors who want precious metals exposure often find that owning miners dilutes the very thesis they are investing in.
But there is a model that sidesteps all of that. Royalty and streaming companies do not operate mines. They provide capital to mining companies in exchange for a percentage of the mine's revenue or the right to buy gold and silver at a steep discount. The mine operator bears all the costs. The royalty holder collects.
Since 2011, a composite index of the major royalty companies (Wheaton Precious Metals, Royal Gold, Franco Nevada, and OR Royalties) has returned roughly 597%, compared to 286% for gold and 160% for the VanEck Gold Miners ETF. When metal prices rise, royalty margins expand without the cost inflation that erodes traditional miner profitability.
The catch? Until recently, nobody was offering this model to the junior end of the market. That is where Empress Royalty comes in.
Built by dealmakers, not geologists
Empress Royalty Corp (TSXV: EMPR | OTCQX: EMPYF) was co founded by people who have spent their careers on the finance side of mining. CEO Alexandra Woodyer Sherron spent a decade at Endeavour Financial, one of the top mining focused investment banking firms in the world, where she structured over US$2 billion in deals. Executive Chairman David Rhodes is an Endeavour Managing Director with over 30 years in mining finance.
That relationship with Endeavour gives Empress access to deal flow, technical expertise, and due diligence capabilities that a company at its size would not normally have. It is a built in competitive advantage.
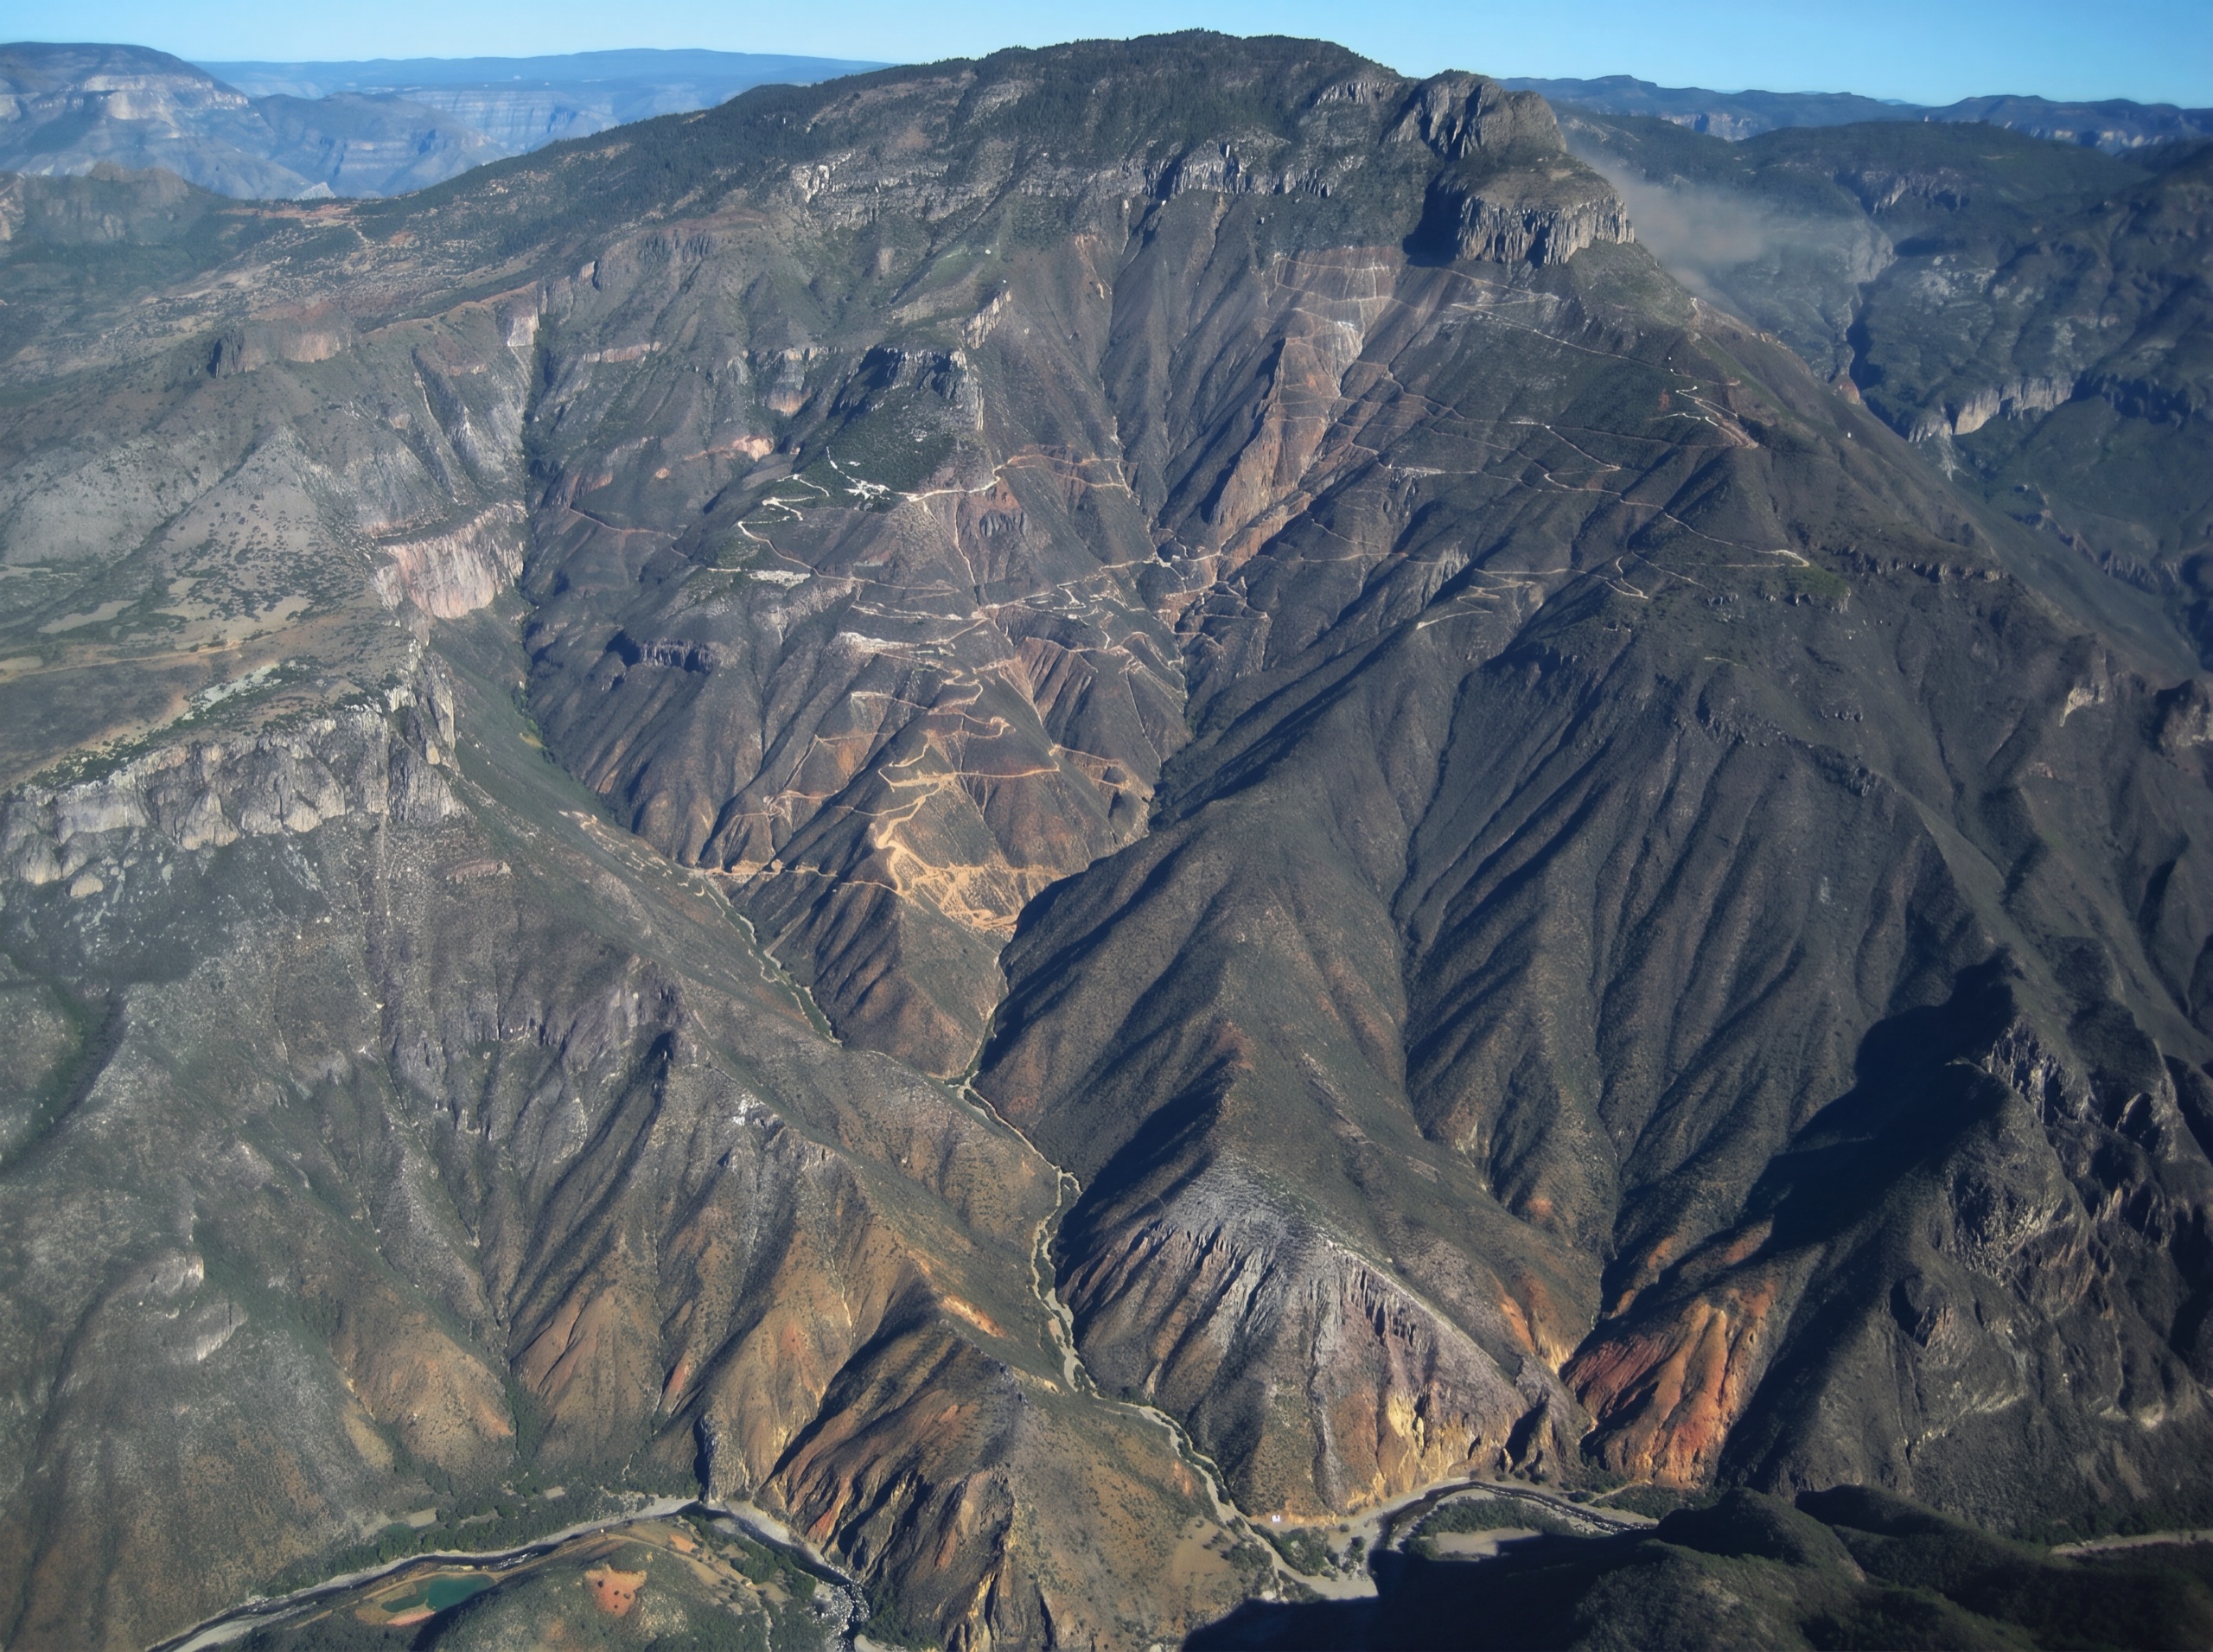
Empress holds producing investments across Mexico, Peru, South Africa, Mozambique, and Côte d'Ivoire.
Four producing assets, real revenue
Empress started by deploying US$23 million into four producing cornerstone investments across four countries. A silver stream in Mexico, a gold stream in Peru, a gold stream in South Africa, and a gold royalty in Mozambique. Combined, those four investments have generated US$47 million in cumulative revenue to date.
Annual revenue tells the growth story. US$1.8 million in 2022. US$3.5 million in 2023. US$8 million in 2024. And a record US$17.2 million in 2025, with positive operational cash flow achieved. First half 2026 revenue more than doubled year over year. This is not a company promising future cash flow. It is already generating it.
The Tongon deal changes the scale
In September 2026, Empress announced the acquisition of a US$62 million gold stream on the Tongon Gold Mine in Côte d'Ivoire. This is the largest transaction in the company's history by a factor of six. The acquisition closed on October 19, 2026.
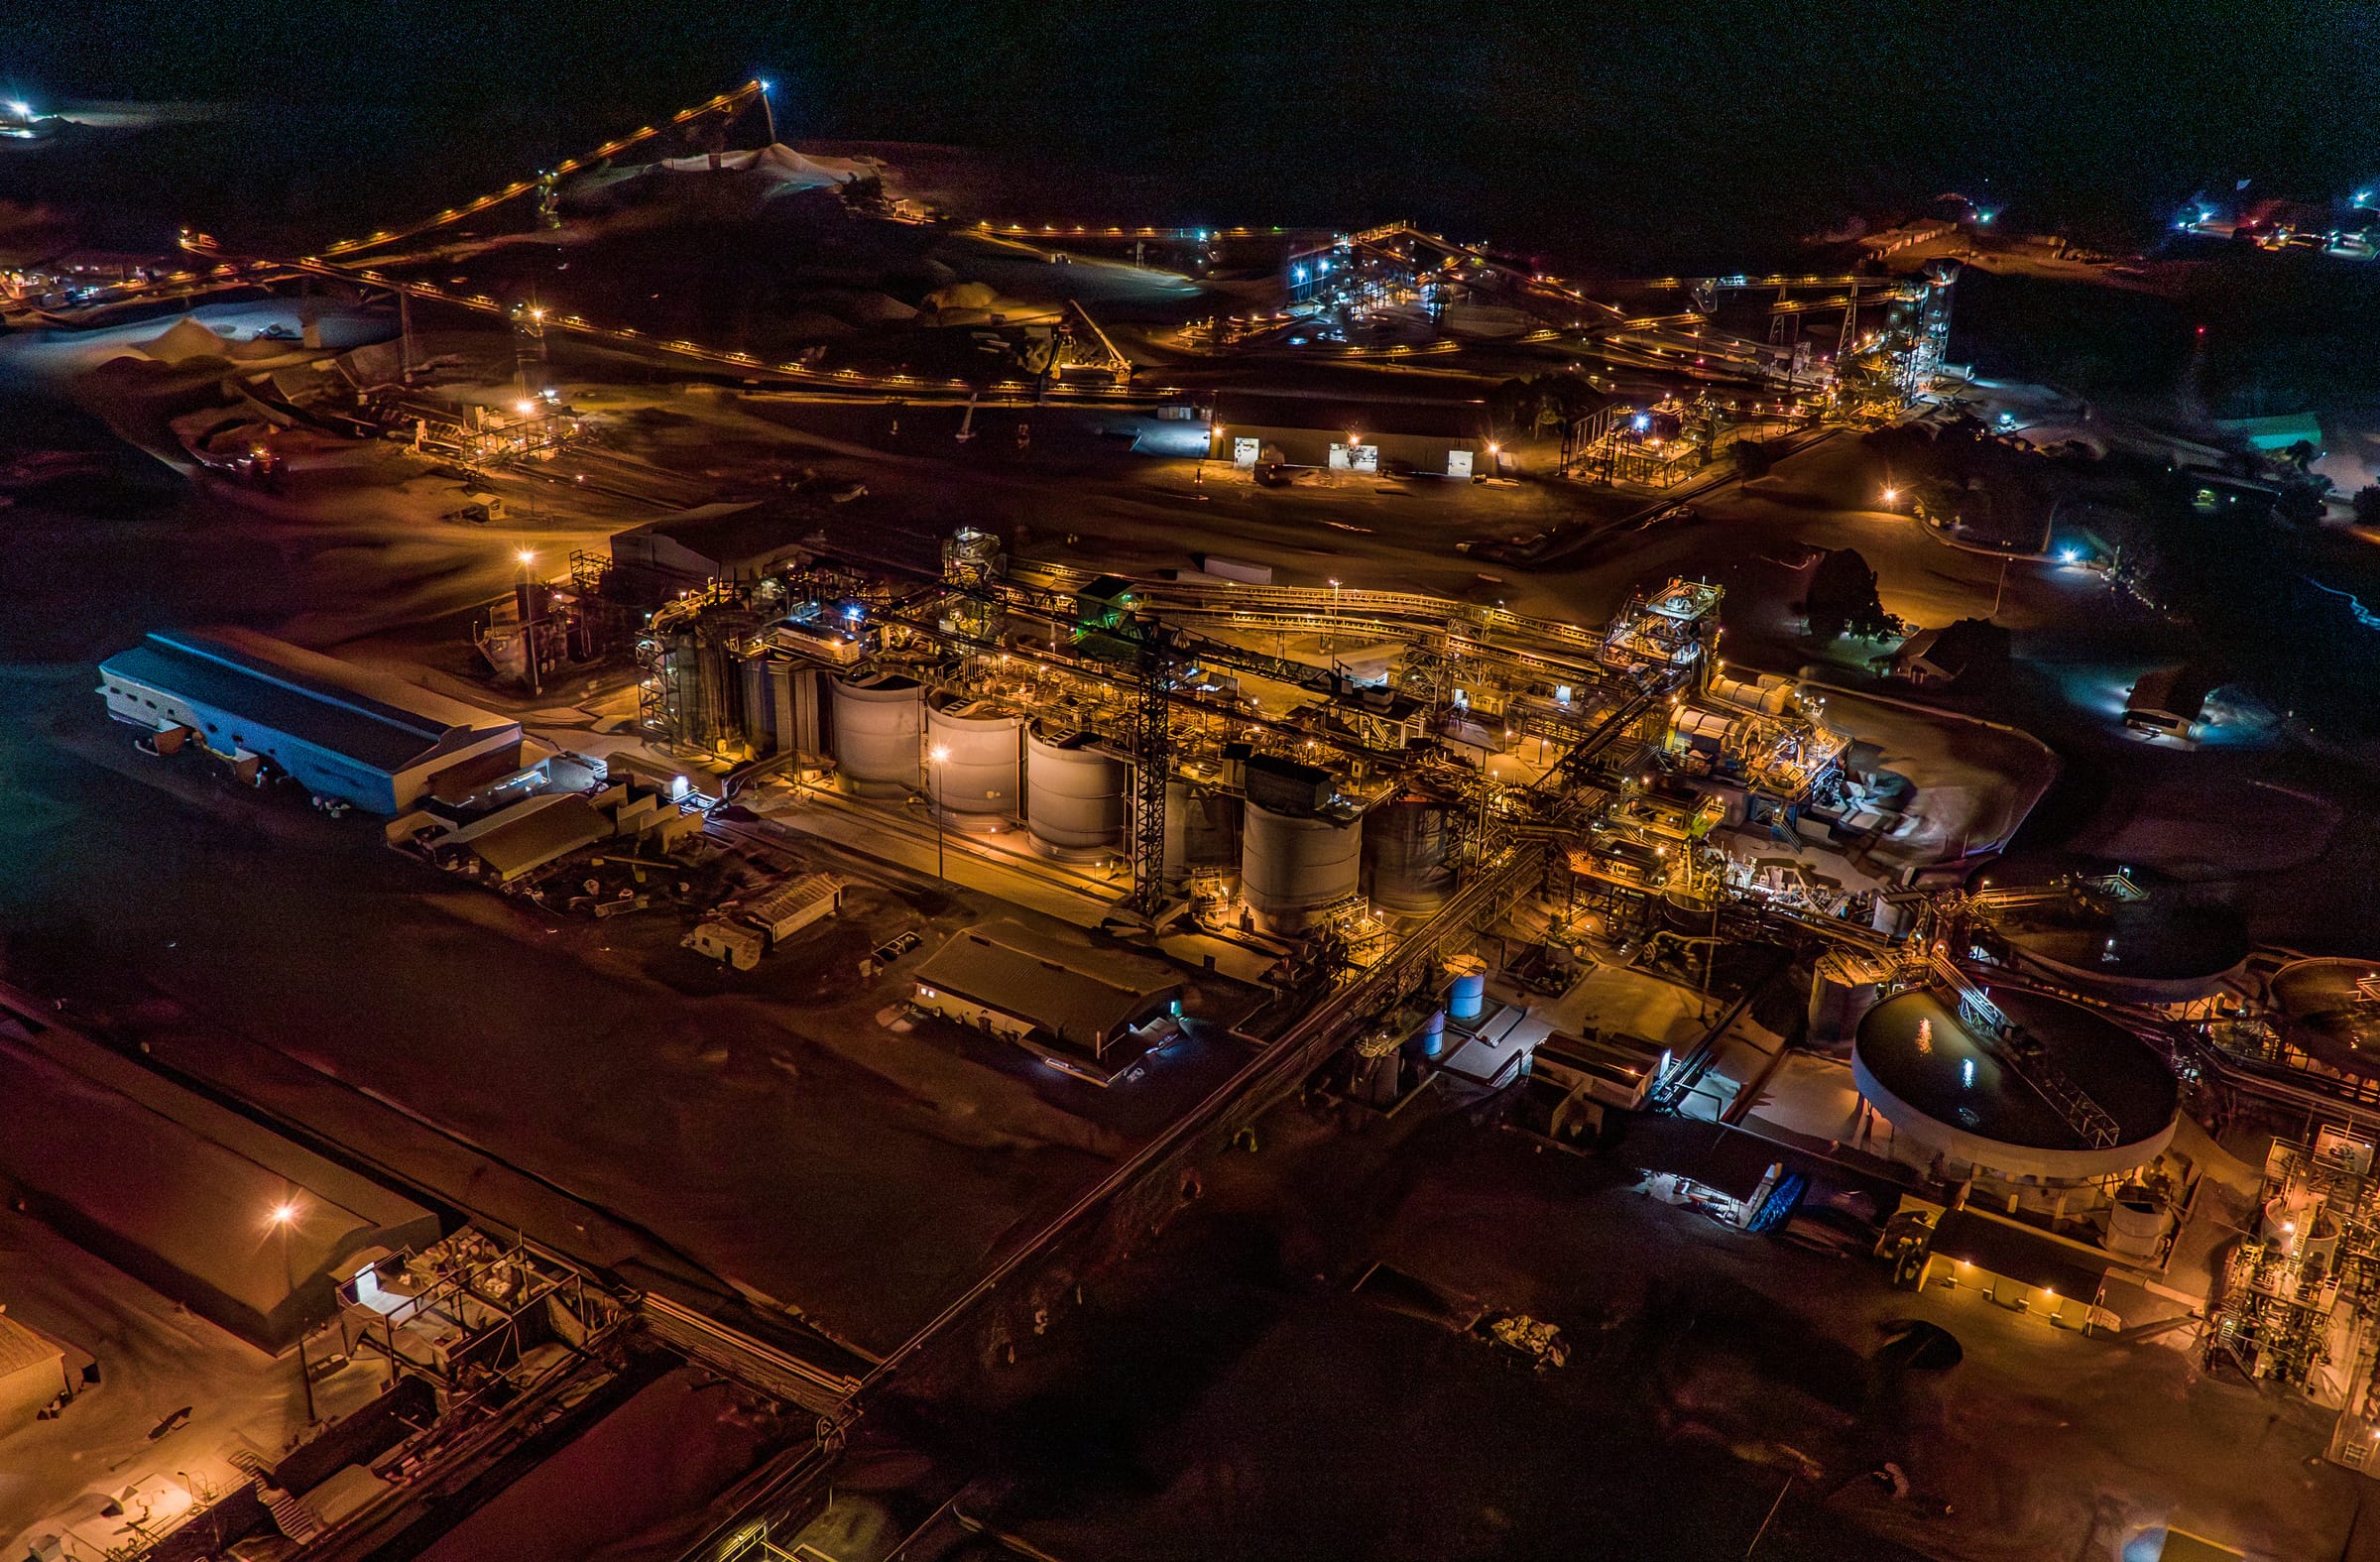
The Tongon Gold Mine in Côte d'Ivoire has produced over 3 million ounces of gold since 2010.
Tongon is not a project waiting to be built. Originally developed by Randgold Resources and operated by Barrick, it entered commercial production in 2010 and has produced over 3 million ounces of gold. Atlantic Group acquired Barrick's 90% interest in 2025.
Empress will initially receive 3.58% of payable production, stepping down to 2.93% and then 0.81% for 29 years, paying just 0.5% of the prevailing gold price per ounce delivered. The transaction was funded by US$55 million from a US$75 million Appian Capital credit facility, with the balance from existing cash. No equity was raised. Shareholder dilution was avoided.
The valuation question
Empress trades at approximately 1.0x NAV (based on management estimates using assumed commodity prices). Its royalty and streaming peer group averages roughly 1.45x. On price to cash flow and price to revenue, Empress currently has the lowest multiples in its peer group, according to 2026 estimates. Revenue has nearly tripled in two years.
Institutional and strategic investors hold roughly 50% of shares. The shareholder register includes names like Rick Rule, Sprott Asset Management, and US Global.
The company also holds 14 pre production exploration royalties acquired from Almadex Minerals in August 2026 for US$2.5 million, adding exposure to projects being advanced by operators including Alamos Gold, Kodiak Copper, Westhaven Gold, McEwen Mining, and Gold Fields.
Bottom line
Empress is a small cap royalty company. It depends on the performance of third party mine operators. Mining carries inherent risks including commodity price volatility, operational challenges, and jurisdictional exposure across Mexico, Peru, South Africa, Mozambique, and Côte d'Ivoire. Revenue from royalty and streaming investments is not guaranteed.
But the model is proven at the top end of the market for a reason. Empress is applying it at the junior scale with real producing assets, record revenue, a transformational acquisition now closed, and a management team with deep institutional finance experience. At current valuations, the market does not appear to have priced in the growth trajectory.
Learn more at empressroyalty.com
TSXV: EMPR | OTCQX: EMPYF
This content is sponsored by Empress Royalty Corp. (TSXV: EMPR / OTCQX: EMPYF). Cashu Group has been compensated for producing this material. Cashu Group is not a registered investment advisor. This is not investment advice. Investing in royalty and streaming companies involves risk, including the potential loss of invested capital. Revenue from royalty and streaming investments depends on operator performance, commodity prices, and other factors beyond the company's control. Forward looking statements are based on management assumptions and are not guarantees of future performance. Always conduct your own research and consult a licensed financial advisor before making investment decisions.